The House Has Been Sitting 45 Days: What Chino and Chino Hills Buyers Should Negotiate
You find a home in Chino or Chino Hills that catches your attention.
You like the neighborhood.
The floor plan works.
The price fits your budget.
Then you notice something:
The house has been sitting on the market for 45 days.
Your first thought might be:
“Let’s offer $50,000 under asking.”
Maybe.
But that’s not where we’d start.
We’d start with a much better question:
Why hasn’t this house sold yet—and what could make this transaction work for both sides?
Because when a property has been sitting for several weeks, the opportunity isn’t necessarily just negotiating a lower price.
You may be able to negotiate the entire transaction:
- Purchase price
- Seller credits
- Closing costs
- Mortgage-rate buydown
- Repairs
- Closing date
- Possession
- Other contractual terms
The goal isn’t to see how much you can take from the seller.
The goal is to determine which terms create the most value for you while giving the seller a transaction they’re willing to accept.
That’s where smart negotiation begins.
Does 45 Days on Market Mean Something Is Wrong With the House?
Not necessarily.
A property can remain on the market for many reasons.
Maybe:
- It was originally overpriced
- Mortgage rates changed
- Buyer demand slowed
- The property needs cosmetic improvements
- Another competing listing attracted the available buyers
- The seller already reduced the price
- The home came on during a slower period
- Buyers simply didn’t see enough value at the original price
That’s why we wouldn’t look at 45 days on market and immediately conclude:
“Something must be wrong with it.”
We’d look at 45 days and ask:
“What has the market been telling this seller?”
That’s a much more useful question.
And understanding the seller’s side can make you a better buyer. We’ve written separately about what Chino and Chino Hills homeowners should evaluate when their listing expires without selling.
Step 1: Study the Price History
Before deciding what to offer, look at the property’s listing history.
Ask:
What was the original list price?
Has the seller reduced it?
How many times?
How large were the reductions?
When was the most recent reduction?
Imagine two Chino homes currently listed at:
$875,000
House A
Originally listed at:
$950,000
Then reduced to:
$925,000
Then:
$899,000
And now:
$875,000
House B
Listed at:
$875,000 from day one.
Those are two completely different negotiation stories.
House A has already received significant market feedback.
The seller has moved $75,000 from the original asking price.
House B may simply need more time.
Days on market matter—but price history gives those days context.
Step 2: Compare the House With What Buyers Can Purchase TODAY
Comparable sales matter.
But as a buyer, don’t look only at houses that sold several months ago.
You also need to know:
“What else can I buy today for the same money?”
If you’re considering an $875,000 Chino home, look at the other homes currently available around that price.
Compare:
- Square footage
- Lot size
- Floor plan
- Location
- Kitchen
- Bathrooms
- Roof
- HVAC
- Electrical
- Flooring
- Landscaping
- HOA
- Property taxes
- Overall condition
- Seller incentives
Then ask:
“If I don’t buy this house, what are my alternatives?”
That question matters.
Because a 45-day listing isn’t automatically a bargain.
If it’s still the best house available for the money, the seller may have more leverage than the days-on-market number suggests.
But if there are three comparable or better homes at similar prices?
Now the buyer may have more negotiating leverage.
Step 3: Find Out What Matters to the Seller
This can completely change the negotiation.
A seller may care about price.
But price may not be their only concern.
Maybe the seller:
- Already purchased another home
- Is relocating for work
- Is retiring
- Is going through a divorce
- Inherited the property
- Is carrying two homes
- Needs proceeds for another purchase
- Wants a particular closing date
- Needs additional time after closing
Buyers shouldn’t assume they know someone’s personal circumstances.
But when information is appropriately available through the transaction, it can help structure an offer.
Suppose the seller’s biggest concern is:
“We need to close quickly.”
And you’re fully underwritten and capable of accommodating that timeline.
That may have value.
Or maybe the seller needs a longer escrow.
If your schedule is flexible, that flexibility may strengthen your offer without requiring you to increase your price.
Sometimes the best negotiation term isn’t money.
Step 4: Don’t Automatically Start With a Lowball Offer
Suppose a Chino Hills home is listed for:
$900,000
Your first instinct might be:
“It’s been sitting 45 days. Let’s offer $875,000.”
That could be appropriate.
But suppose the seller is willing to give up approximately $15,000 to make the transaction work.
Now there may be several ways to structure the negotiation.
You might negotiate:
A lower purchase price
or
Seller-paid eligible closing costs
or
A financing concession that could potentially help reduce your mortgage cost
or
Repairs
or
A combination of terms.
Which is best?
Run the numbers first.
Don’t negotiate $15,000 simply because $15,000 sounds good.
Determine where that $15,000 creates the greatest benefit for your family.
Step 5: Could a Seller Credit Be Better Than a Price Reduction?
Sometimes.
Suppose the seller is willing to give up:
$15,000
You could ask for a $15,000 reduction in purchase price.
But depending on your financing, another option could involve using an allowable seller contribution toward eligible closing costs or financing expenses.
Here’s the important part:
A $15,000 price reduction and a $15,000 seller credit do not necessarily provide the buyer with the same financial benefit.
Ask your lender to run both scenarios.
Scenario A
$15,000 lower purchase price
Scenario B
$15,000 seller credit structured within your loan guidelines
Then compare:
- Cash needed at closing
- Monthly payment
- Interest rate
- Long-term cost
- Break-even period
Now you’re negotiating with actual numbers instead of assumptions.
Step 6: Understand What a Seller Credit Can—and Cannot—Do
A seller credit isn’t simply money the buyer gets handed at closing.
How it can be used depends on the loan program, financing and transaction.
Depending on the circumstances, an allowable seller contribution may potentially help with eligible:
- Closing costs
- Prepaid expenses
- Certain lender costs
- Mortgage-rate buydowns
But loan programs have requirements and limits.
That’s why you want your lender involved before writing the offer.
Ask:
How much seller credit can I actually use?
What expenses can it cover?
Could some of it be used toward an eligible rate buydown?
Would I actually benefit from the full amount?
A $20,000 credit isn’t particularly valuable if your financing structure doesn’t allow you to effectively use the entire amount.
Negotiate what you can actually use.
Step 7: Look at the Mortgage Payment, Not Just the Purchase Price
This is especially important in today’s market.
Buyers aren’t simply shopping for a house.
They’re also shopping for a:
Monthly housing payment.
That payment can include:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- HOA dues, if applicable
- Other applicable housing expenses
So don’t focus only on:
“How much did we get off the asking price?”
Also ask:
“What is our actual monthly payment?”
And:
“How much cash will we need to close?”
A buyer may get excited about negotiating $10,000 off the purchase price.
But depending on the financing, that may not dramatically change the monthly payment.
An appropriately structured seller concession may potentially affect the buyer’s immediate costs differently.
That’s why purchase price is only one part of the negotiation.
Mortgage rates are another part of that equation. We’ve created a separate guide explaining what Federal Reserve rate changes actually mean for Chino and Chino Hills home buyers and sellers.
Step 8: Should You Ask for a Mortgage-Rate Buydown?
It’s certainly something worth evaluating with your lender.
There are different types of mortgage-rate buydowns, and the structure matters.
Instead of simply asking:
“Can the seller buy down my rate?”
Ask your lender:
How much would it cost?
What would it do to my payment?
Is the reduction temporary or permanent?
What are the qualification requirements?
What is the break-even point?
Would we benefit more by using the seller contribution somewhere else?
That last question matters.
A rate buydown isn’t automatically the best use of a seller concession.
Run the complete financing scenario.
Step 9: Don’t Forget About Repairs
A house sitting 45 days may also create opportunities during the inspection and negotiation process.
That doesn’t mean:
“Ask the seller to fix everything.”
An older house is still an older house.
But if inspections reveal legitimate concerns involving:
- Roof
- HVAC
- Plumbing
- Electrical
- Water heater
- Drainage
- Structural components
- Safety issues
you should understand what you’re purchasing.
Depending on the property, contract and circumstances, the parties may negotiate repairs, credits, price adjustments or another solution.
The goal isn’t to turn a 25-year-old house into a brand-new house.
The goal is to understand the property’s condition and decide whether the complete transaction still makes sense.
Step 10: What If the Seller Already Reduced the Price Twice?
This is where buyers need to be careful.
A seller reducing the price twice does not automatically mean:
“They’re desperate.”
It could mean the seller finally adjusted to market value.
Imagine a property was:
$950,000
then:
$925,000
and now:
$899,000.
Comparable properties suggest it’s worth approximately:
$900,000.
The seller may have finally reached the right price.
Offering:
$825,000
simply because the house has been sitting could accomplish nothing except losing the property.
Instead, evaluate:
- Comparable sales
- Current competition
- Price history
- Property condition
- Recent reductions
- Available seller information
- Your alternatives
Then build the offer.
Days on market create information—not an automatic discount.
Don’t Ignore 30-, 45- and 60-Day Listings
Most buyers love the brand-new listing.
It hits the market Thursday.
Everybody sees it.
Open house Saturday.
Offers Monday.
But here’s something we’d encourage Chino and Chino Hills buyers to do:
Look where everyone else stopped looking.
Ask your agent to show you properties that have been available:
21+ days
30+ days
45+ days
and even:
60+ days.
Some will have problems.
Some will still be overpriced.
Some won’t fit your needs.
But occasionally you’ll find a perfectly good property that simply:
Started too high.
Had poor timing.
Needs cosmetic work.
Was overlooked.
Has a seller whose circumstances have changed.
That’s where an opportunity may exist.
What Can a Longer Listing Tell You About the Seller’s Side?
Imagine a homeowner listed the property because they already purchased their next house.
Now their original home has been sitting for 45 or 60 days.
They may be paying:
- Two mortgage payments
- Two property-tax obligations
- Two insurance policies
- Utilities
- HOA dues
- Maintenance on two properties
That doesn’t mean they’re desperate.
But carrying two properties has a real cost.
That’s why we’ve written separately about what homeowners should consider when they’ve already moved out of their Chino or Chino Hills home and are still paying for two houses.
Understanding that perspective reinforces an important point:
The seller may care about certainty and timing—not only price.
A strong buyer may be able to create value through a combination of price, financing strength, timeline and contractual terms.
What About Chino and Chino Hills Specifically?
Don’t assume every property in either city behaves the same way.
Even within Chino or Chino Hills, buyer demand can change dramatically based on:
- Neighborhood
- School area
- Price range
- Lot
- Floor plan
- Condition
- HOA
- Property type
- Competition
That’s why we wouldn’t tell a buyer:
“It’s Chino Hills, so offer 5% below asking.”
Or:
“It’s Chino, so you have to pay full price.”
Neither approach is sophisticated enough.
Negotiate the property—not the ZIP code.
The right offer depends on the specific house and the market surrounding that house.
Our 45-Day Listing Negotiation Checklist
Before writing an offer on a Chino or Chino Hills home that’s been sitting, we’d want answers to these 10 questions:
1. What was the original list price?
2. How many price reductions have there been?
3. When was the most recent reduction?
4. What do the best comparable sales support?
5. What competing homes can we buy today?
6. What condition is the property in?
7. What information do we appropriately know about the seller’s priorities?
8. What seller credit can our financing actually use?
9. Would a price reduction, closing-cost credit or eligible financing concession help us more?
10. How badly do we actually want this house?
That last question matters.
Because negotiation isn’t happening in a vacuum.
There may be another buyer looking at the same opportunity.
What If It’s the Perfect House?
This is where buyers can sometimes negotiate themselves right out of the home they actually want.
Suppose the property:
- Fits your family
- Fits your budget
- Is in the neighborhood you want
- Has the floor plan you need
- Has limited comparable alternatives
- Is reasonably priced
And you’ve been looking for six months.
Don’t lose the right house because you became obsessed with being able to tell your friends:
“We got them down another $10,000.”
The purpose of negotiation isn’t to beat the seller.
It’s to create terms you’re comfortable accepting on a home you actually want to own.
There’s a difference.
Frequently Asked Questions
Is 45 days a long time for a house to be on the market in Chino or Chino Hills?
It means the property has received meaningful market exposure, but it doesn’t automatically indicate a problem. Evaluate the property’s price history, condition, competition, recent comparable sales and any price reductions.
Should I offer below asking on a Chino home that’s been sitting for 45 days?
Possibly. But don’t choose an arbitrary discount simply because of days on market. Determine what the property is realistically worth and structure the offer around the complete transaction.
Can I ask a Chino or Chino Hills seller to pay closing costs?
Seller contributions may be negotiable, subject to the purchase agreement and applicable loan-program requirements. Your lender should determine how much credit your financing allows and how it can be used.
Is a seller credit better than a lower purchase price?
Sometimes. A price reduction and seller credit can affect the buyer differently. Have your lender calculate both scenarios so you can compare cash needed to close, monthly payment and long-term costs.
Can a seller help buy down my mortgage rate?
Potentially, subject to the loan program and transaction. Your lender should explain whether a seller-funded buydown is available, how it would work and any applicable limits.
Should I ask for repairs too?
Inspection findings may create additional negotiation points. Whether to request repairs, credits or another solution depends on the property’s condition, contract and circumstances.
Does a price reduction mean the seller is motivated?
Not necessarily. A reduction tells you the seller changed the asking price. It doesn’t necessarily tell you why. The new price may simply reflect current market value.
Should I look at homes that have been listed for 60 days or longer?
Absolutely. Longer days on market can be worth investigating. Some properties have legitimate problems, while others may simply have started overpriced, need cosmetic improvements or have been overlooked.
Final Thoughts
If a Chino or Chino Hills home has been sitting for 45 days, don’t automatically ask:
“What’s wrong with it?”
Ask:
“What opportunity might exist here?”
Then investigate:
Price history.
Comparable sales.
Current competition.
Property condition.
Seller priorities.
Financing.
Seller credits.
Repairs.
Closing timeline.
And most importantly:
What terms actually benefit your family?
Because the best negotiation isn’t necessarily:
“We got $25,000 off the price.”
It may be:
“We got the right house, at a price we were comfortable with, with terms that made the complete transaction work for our family.”
That’s a much better definition of winning.
And there’s another side to every negotiation. If you want to understand some of the numbers a homeowner may be considering when evaluating your offer, our guide explaining how much it costs to sell a house in Chino and how sellers calculate estimated net proceeds explains that side of the transaction.
Leticia and Alberto Sotomayor are Realtors helping buyers, sellers and homeowners throughout Chino, Chino Hills, the Inland Empire and Orange County understand their options and negotiate around their family’s actual needs.
Don’t just negotiate the price. Negotiate the entire deal.
Real-estate contracts, mortgage programs, rates, seller-contribution limits and financing requirements can change and vary by transaction. Buyers should review financing options and specific calculations with their qualified mortgage professional and review contractual, legal or tax questions with the appropriate professionals.
FROM OUR BLOG
Your Chino or Chino Hills Listing Expired—but Your Reason for Moving Didn’t
Your Chino or Chino Hills Listing Expired—but Your Reason for Moving Didn’t Your home was listed for sale. You cleaned it. Prepared it. Allowed strangers to walk through it. Maybe you rearranged your schedule for showings. Maybe you left the house every weekend for open houses. Maybe you reduced the
How Much Does It Cost to Sell a House in Chino, CA? Seller Costs & Net Proceeds Explained
How Much Does It Cost to Sell a House in Chino, CA? If you're thinking about selling your home in Chino, one of the first questions you probably have is: “How much is this actually going to cost me?” That's the right question—but there's an even more important one: “After the mortgage, selling expen
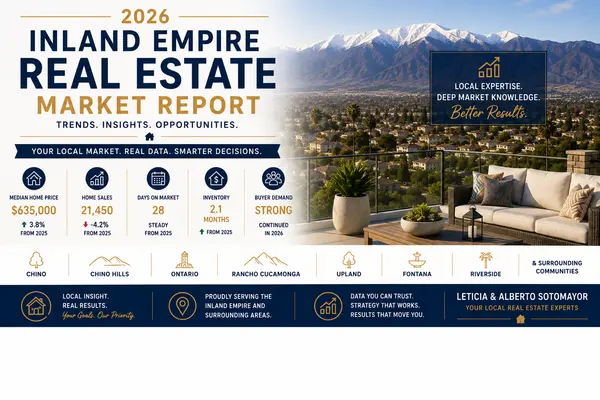
2026 Inland Empire Real Estate Market Report: What Buyers and Sellers Need to Know
The five-city corridor of Chino, Chino Hills, Ontario, Eastvale, and Upland is the most practical mid-range option for homeownership in Southern California. Prices across these cities range from around $675,000 in Ontario up to just over $1,000,000 in Chino Hills. That is still $200,000 to $400,000